Why Read the Rules, Not the Forecasts
Most writing about where this industry is headed is guesswork dressed as insight. Nobody knows which firms survive the next two years, and anyone claiming otherwise is selling something.
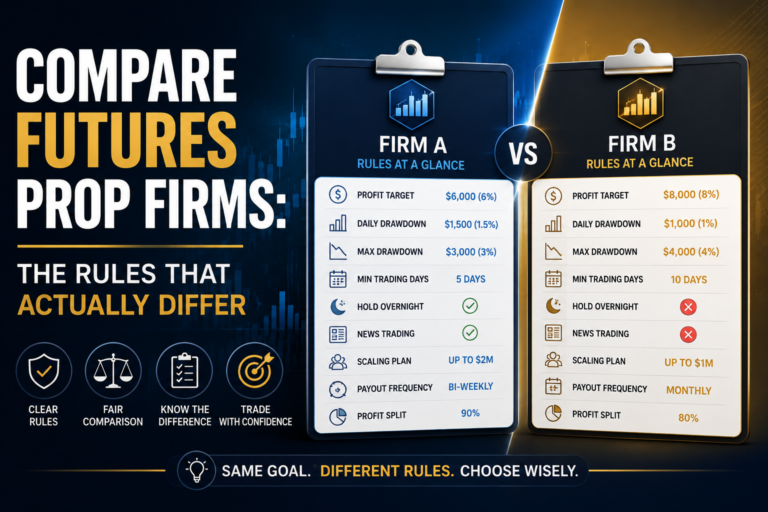
What can be known is what firms are actually changing in their terms. Rules are published, dated and comparable, and when several firms independently move the same direction, that tells you more than any forecast.
We read the terms of sixteen futures prop firms for our reviews. Six shifts show up repeatedly, and every one of them changes what a trader should look for.
Shift One: Intraday Trailing Drawdown Is Losing
This is the clearest movement in the industry and the most important.
What intraday trailing does. Your failure floor follows your peak unrealised equity in real time. A trade runs up 2,000 dollars, you close it flat, and the floor has permanently moved up 2,000 dollars. You produced nothing and lost that much room.
What is changing. Firms are moving to End of Day logic, where the floor only updates on your closing balance. Intraday swings stop counting. Several firms we review now use End of Day across every account type they offer, including instant funding, which used to carry the strictest drawdown a firm had.
Tradeify retired its intraday trailing model entirely and now runs End of Day on all plans. Alpha Futures, AquaFutures and Blue Guardian all use it. Bulenox offers it as a checkout choice against intraday trailing.
Why it is happening. Intraday trailing fails traders who are trading correctly, which produces complaints, poor reviews and churn. A firm making money from evaluation fees does not actually benefit from a rule that fails competent traders at random.
What it means for you. End of Day drawdown is now common enough that accepting intraday trailing should require a reason. If a firm offers it, ask what you get in exchange.
The three structures are compared on the comparisons hub, and Chapter 06 on margin and survival covers the maths.
Shift Two: The Drawdown Lock Is Becoming Standard
A newer development, and underreported.
What it is. The trailing stops permanently once the floor reaches your starting balance, or starting balance plus a small cushion. From that point the account is static drawdown.
Who does it. Alpha Futures locks when the floor reaches the starting balance. Bulenox locks at starting balance plus 100 dollars. Tradeify locks once an End of Day balance exceeds the start by the drawdown plus 100. Blueberry Futures goes further and triggers its lock at 4 percent profit rather than waiting for the floor to catch up.
Why it matters more than it sounds. A locked floor converts the hardest structure in the industry into the most forgiving one, partway through the account. It means the difficult phase is temporary, which changes the correct strategy completely: size small until the lock, then trade normally.
The direction of travel. Blueberry’s approach of triggering the lock early rather than waiting is the interesting one. If other firms follow, the trailing phase shortens across the industry.
Shift Three: The Filter Is Moving to the Payout Gate
This one works against traders and nobody announces it.
The old structure. Hard evaluation, then a funded account with relatively simple payout terms. The test was before the money.
The new structure. Easier evaluations, sometimes passable in one or two days, paired with a payout gate carrying a consistency rule, a minimum profit threshold, a minimum number of qualifying trading days and often a per request cap.
The evidence. Several firms now advertise passing in as little as one to two days. At the same time, consistency rules have become near universal, and winning day requirements have appeared, where a session only counts if it cleared a minimum profit, commonly 100 to 200 dollars.
Blueberry Futures defines an Active Trading Day as one generating at least 0.5 percent profit. That is a materially higher bar than counting any day with a filled order, and it stretches the real timeline considerably.
Why it is happening. An easy evaluation sells more accounts. A hard payout gate protects the firm from paying out on results it does not trust. Moving the filter after the purchase is commercially rational and entirely legal, and the terms disclose it.
What it means for you. Stop comparing firms on how hard the evaluation looks. Compare on what sits between you and your first cleared payout. That is where the difficulty now lives, and it is several pages into the terms rather than on the pricing page.
How a futures prop firm works follows one account through both stages with the numbers shown.
Shift Four: Plan Proliferation
Firms are no longer selling one product.
The scale of it. Elite Trader Funding offers six evaluation models with different drawdown types, daily loss rules and time limits. Tradeify runs three distinct paths. Alpha Futures runs two with genuinely different payout mechanisms. MyFundedFutures runs four.
The genuine upside. A trader who holds overnight, or who needs a static floor, or whose profits concentrate into a few sessions, can now find a product built for that. Five years ago those traders had almost no options in futures prop.
The real cost. Evaluating a firm properly now means reading several sets of terms rather than one. The cheapest listed plan is frequently the one with the strictest drawdown, which is not a coincidence. Traders who choose on price inside a multi plan firm reliably choose wrong.
A side effect worth knowing. Plans get renamed. Tradeify’s instant funding product was called Straight to Funded and is now Lightning Funded, with rule changes alongside. MyFundedFutures plan names differ across nearly every source describing them. Any guide older than a few months may be describing products that no longer exist under those names.
Shift Five: Cost Is Moving Away From the Entry Price
The advertised price is becoming less informative every year.
Where the money actually sits now. Activation fees charged on passing, commonly 100 to 300 dollars. Monthly market data charges that continue for as long as you hold the account. Reset fees. Withdrawal buffers, where you must earn roughly your drawdown amount and leave it in the account before taking anything out.
The counter movement. Some firms compete specifically on this. Blue Guardian charges no activation fee and no data fees at the funding stage, with a refundable evaluation fee. AquaFutures uses a one time fee refundable on the fourth payout. OneUp Trader includes data and unlimited resets, and splits its fee so half is only due on funding approval.
The split in the market. Two models are emerging. One advertises a very low entry price and recovers cost after you pass. The other charges more upfront and bundles what the first charges separately. The second is usually cheaper in total, and almost always looks more expensive at checkout.
What it means for you. Entry price comparison is now actively misleading. The figure that matters is total cost to a cleared payout, which routinely runs three to five times the advertised price. Our comparisons hub is built around that number, and current codes are on the coupons hub.
Shift Six: The Two Tier Funded Account
The newest structure, and the one most likely to confuse buyers.
How it works. Passing an evaluation places you in a simulated funded account where payouts are real money but the trading is not on live capital. A separate programme, usually invitation only and at the firm’s discretion, moves top performers to real capital.
Where it is visible. Elite Trader Funding runs exactly this, with sim funded accounts and a LIVE ELITE programme above them. Several other firms describe funded accounts as simulated in their own disclaimers.
The counterintuitive part. The split frequently moves against you on promotion. Sim funded accounts commonly pay up to 100 percent, while live capital programmes pay 80/20. Traders expecting the split to improve on reaching real funding find it goes the other way.
The transparency question. Firms stating plainly that funded accounts are simulated are disclosing more than firms using the word funded without qualification. That disclosure is becoming more common, which is a genuine improvement, but it is not yet universal.
What it means for you. Ask which model applies before buying. If reaching live capital matters to you, ask what the published criteria are. Where progression is discretionary with no stated criteria, treat it as a possibility rather than a plan.
What We Cannot Tell You
Being straight about the limits of this page.
We do not know which firms survive. Prop firms close, get acquired and rebrand frequently, and no amount of terms analysis predicts solvency. This is a real reason not to concentrate everything at one firm.
We do not know what regulators will do. Evaluation payments currently sit outside the customer funds protection framework that applies to registered futures commission merchants. The CFTC customer protection resources set out what that framework actually covers. Whether that position changes is not something we will speculate about, and we track developments as they happen in NewsFlash.
We do not know how long these shifts continue. Six firms moving one direction is a trend. It is not a guarantee the seventh follows, or that the first six do not reverse.
What This Means for Choosing a Firm Today
Four practical consequences of the six shifts above.
- Drawdown type is now a genuine choice rather than something you accept. Enough firms offer End of Day with a lock that taking intraday trailing should buy you something specific.
- The payout gate deserves more attention than the evaluation. That is where the difficulty moved, and it is the part most buyers never read.
- Inside a multi plan firm, the plan matters more than the firm. Read all the plans, not the cheapest one.
- Total cost to a payout is the only honest price comparison. Entry price now tells you almost nothing.
How to pick a firm for your trading style works through this from your own approach backwards, and every firm we review is listed with the facts needed to shortlist.
Frequently Asked Questions
1. Is prop trading growing or shrinking?
Futures prop firms continue to launch and existing firms continue to expand their product ranges, which indicates an active market. Individual firms close, get acquired or rebrand regularly, so sector level activity and any specific firm’s longevity are separate questions.
2. Are prop firm rules getting easier or harder?
Both, in different places. Evaluations have become easier, with some firms allowing a pass in one or two days. Payout conditions have become stricter, with consistency rules, minimum profit thresholds and qualifying day requirements now common. The difficulty moved rather than reduced.
3. Why are firms switching to End of Day drawdown?
Intraday trailing drawdown penalises traders for unrealised profit given back during a session, which fails competent traders and produces churn. End of Day logic measures only closing balances, which is less punishing and reduces the complaints and account losses that come with the stricter mechanism.
4. What is a drawdown lock?
A drawdown lock stops the trailing permanently once the floor reaches the starting balance or a defined threshold above it. The account then behaves as static drawdown for the remainder of its life, which makes the difficult trailing phase temporary rather than permanent.
5. Why do prop firms now offer so many plans?
Different trading styles need different rules, and multi plan structures let a firm serve swing traders, scalpers and position traders from one brand. The cost is complexity, since evaluating such a firm properly requires reading several sets of terms rather than one.
6. What is a simulated funded account?
A simulated funded account operates in a demo environment using live market data, with payouts paid as real money by the firm. Several firms run these alongside a separate live capital programme that top performers may be invited into, usually at the firm’s discretion.
7. Why would a profit split decrease on a live account?
Simulated funded accounts commonly pay up to 100 percent because the firm is paying from its own revenue rather than market gains. Live capital programmes carry real market exposure for the firm, which is typically reflected in a lower trader share such as 80/20.
8. Are prop firm fees getting cheaper?
Entry prices have fallen while costs after passing have risen, including activation fees, market data charges and withdrawal buffers. Some firms compete specifically by removing those charges, which usually produces a lower total cost despite a higher advertised price.
9. Will prop firms become regulated?
Evaluation payments currently sit outside the customer funds protection framework applying to registered futures commission merchants, and we do not speculate on whether that changes. Regulatory developments affecting this sector are tracked as they occur rather than predicted.
10. How often do prop firms change their rules?
Frequently, and often without announcement. Plan names change, drawdown parameters are revised and payout conditions are updated, sometimes leaving a firm’s own documentation contradicting itself. Any comparison without a verification date should be treated cautiously.
11. Should I spread accounts across several firms?
Concentration at one firm carries counterparty risk that no analysis of published terms can measure, since evaluation payments are not held in segregated accounts. Spreading across firms reduces that exposure, subject to each firm’s rules on multiple accounts.
12. What should I watch for in the next year?
Whether drawdown locks trigger earlier across more firms, whether payout gates continue tightening as evaluations ease, and whether the gap between simulated and live funded accounts is disclosed more consistently. All three are observable in published terms as they change.
13. Is instant funding becoming more common?
Instant funding products are now offered by a significant number of futures prop firms, and some now pair them with End of Day drawdown rather than the strictest available structure. The payout conditions on these accounts remain the mechanism by which firms manage the removed evaluation.
14. Are consistency rules getting stricter?
Thresholds vary widely, from around 20 percent at the strictest to none at all on some funded account types. A newer approach applies progressive consistency, tightening the first payout and relaxing later ones, which prices the firm’s exposure on an unproven account more honestly.
15. How do I keep up with rule changes?
Each firm’s own terms page is the only authoritative source, and verification dates matter more than content age. We track material changes across the industry in our news section and carry a last verified date on every review and comparison page.
In Summary
The industry is getting more forgiving where it is visible and stricter where it is not.
Drawdown mechanics have improved genuinely, and the locks arriving across several firms are a real gain for traders. At the same time, the filter has moved from the evaluation to the payout gate, where fewer buyers look, and cost has moved from the entry price to everything that follows it.
Both movements point to the same practical advice. Read the funded account terms, not the pricing page.
Next step: see how each firm handles these six areas on the rules comparison, or compare every firm we score on the factors that follow from them.